
Hotel Insurance Online :: News
SHARE

Share this news item!

Disaster Recovery Gap Puts Retail Resilience in Focus

New QBE-commissioned research shows severe weather can affect small business numbers well beyond the clean-up phase

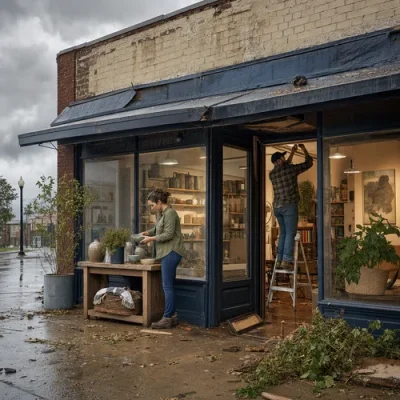
Disaster Recovery Gap Puts Retail Resilience in Focus?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Fresh research commissioned by QBE and conducted by Oxford Economics Australia has put a longer lens on disaster recovery for small businesses, finding that the economic effect of floods, bushfires and cyclones can deepen well after the initial clean-up.
For Australian retailers, the message is practical: recovery planning and insurance settings need to reflect more than the first few weeks after a major event.

The report, released in October 2026, examined seven significant Australian disasters between 2018 and 2023 and compared affected communities with similar areas that were not hit by a major disruption. It estimated that affected regions had around 3% fewer small and medium enterprises than expected in the year of an event, widening to 4% after one year and 9% after two years. By the third year, the gap was still around 7%.

Those figures do not mean every missing business was directly destroyed by weather. QBE’s own commentary notes that disaster can slow new business formation, reduce investment and exhaust the reserves that allow firms to keep trading in the immediate aftermath. Even so, the pattern is important for shop owners because retail recovery often depends on factors outside the shop itself: customer foot traffic, staff availability, freight routes, nearby anchor tenants and whether the broader shopping precinct comes back to life.

This is where insurance design and business continuity planning meet. Property cover may help with damaged fit-out, stock or equipment, depending on the policy. Business interruption cover, where held, raises a different question: how long would revenue realistically take to recover after a major loss? A short indemnity period may look affordable at renewal, but it can be tested if rebuilding approvals, replacement stock, supplier delays or a damaged local economy stretch recovery over many months.

Retailers reviewing common retail disasters should also look beyond the headline insured event. Useful checks include current stock values, seasonal peaks, replacement cost assumptions, lease obligations, flood or storm exclusions, waiting periods, sub-limits and whether temporary trading costs would be recognised. Educational tools can help businesses estimate replacement values, but final cover decisions still depend on policy wording, insurer appetite and the individual business circumstances.

The report is also a reminder of uncertainty. It was commissioned by an insurer and analyses community-level outcomes, not individual claim results. However, its broader point is difficult to ignore: a disaster recovery plan that ends when the doors reopen may be too narrow. For shop owners in exposed locations, resilience is increasingly about surviving the second year as well as the first week.

Published:Thursday, 5th Nov 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Insurance News

Underpaid Claims Highlight the Detail Behind Income Protection Benefits
18 Nov 2026: Paige Estritori
A newly published Life Code Compliance Committee sanction has highlighted a practical but often overlooked issue for Australians relying on personal insurance: having a claim accepted is not the same as receiving every benefit correctly calculated and paid. The de-identified case, published on 16 November 2026, concerned an unnamed life insurer that underpaid about $1.6 million, including interest, across 66 income protection and death benefit claims. - read more
Live Music Inquiry Highlights Public Liability Pressure for Venues
18 Nov 2026: Paige Estritori
A NSW parliamentary inquiry into the state of live music has put public liability insurance back in the spotlight for venues, festivals and event operators, after its final report identified insurance affordability as a significant operating pressure and recommended further work on reform options. - read more
Live Music Insurance Reform Call Has Wider Lessons for Public-Facing Businesses
18 Nov 2026: Paige Estritori
A NSW parliamentary inquiry into the state of live music has put insurance affordability back in the spotlight, with its final report tabled on 9 November 2026 identifying public liability insurance as a major cost burden for venues and festivals. The recommendation does not change premiums immediately, but it gives business owners a useful signal: governments, insurers and industry groups are still grappling with how public-facing risks are priced, documented and managed. - read more
Storm Claims Put Policy Details Under Fresh Pressure
18 Nov 2026: Paige Estritori
The Insurance Council of Australia’s expanded Significant Event declaration for severe storms in Queensland and New South Wales is a timely reminder that insurance is tested in the messy aftermath of damage, power loss and disruption, not just at renewal time. By 17 November 2026, insurers had received more than 7,500 claims linked to severe weather from 11 to 17 November, with damage ranging from torn roofs and broken fences to water entry, hail impacts and spoiled food after outages. - read more
Bakery Dispute Shows Supplier Risk Can Interrupt Trade
18 Nov 2026: Paige Estritori
A recent business interruption dispute involving a bakery has given restaurant and cafe operators a timely reminder that disruption does not always start inside the insured premises. The Australian Financial Complaints Authority found in favour of a bakery retail business after its insurer declined a claim linked to a fire at the premises of its sole supplier, bringing supplier-dependency wording into sharp focus for hospitality businesses that rely on specialist producers, central kitchens, roasters, wholesalers or delivery partners. - read more


Hotel Insurance Articles

Claims Made Simple: What to Expect When Filing Hotel Insurance Claims
Running a hotel is a complex operation that involves many moving parts. From welcoming guests to maintaining the property, there's a lot to manage. One critical aspect that often flies under the radar is hotel insurance. This form of insurance plays a crucial role in safeguarding your business from unforeseen events that could disrupt operations or impact your financial health. Whether it's damage from natural disasters or unexpected liabilities, insurance is your safety net. - read more
Hotel Insurance Requirements in Australia: Legal and Contractual Considerations
Australian hotel operators may face insurance-related obligations from legislation, leases, lenders, liquor licensing, contracts and risk management needs. This guide explains the difference between compulsory, commonly required and optional covers. - read more
Disability Income Protection: What Every Hotel Operator Needs to Know
Running a café is a rewarding yet challenging endeavor. With the hospitality industry being fast-paced and ever-changing, café owners often face unique financial challenges. Operating in an industry that is both physically demanding and unpredictable can sometimes lead to unforeseen circumstances that affect the stability and success of your business. - read more
What Does Hotel Insurance Cover in Australia?
Hotel insurance in Australia can combine several types of cover, including property, liability, stock, business interruption, vehicles and other risk protections. This guide explains what each cover type generally protects and what hotel operators should check before choosing a policy. - read more
The Role of Business Interruption Insurance in Sustainable Hotel Operations
Business interruption insurance is a policy that covers the loss of income a business suffers after a disaster. While property insurance covers the physical damage to a business, business interruption insurance covers the profits that are lost. It ensures that a company's revenue stream can continue even if its operations are halted due to unexpected events. - read more

Knowledgebase
Elimination Period:
The time period between an injury and the receipt of benefit payments from an insurer, particularly in disability insurance.